Category: Accounting

  • Early Warning Signs of Financial Crisis

    Early Warning Signs of Financial Crisis

       
    Early Warning Signs of Financial Crisis

    What They Are, Causes, & How to Avoid Them

    Financial crisis occurs when a business is unable to meet its financial obligations, including payment of salaries, acquiring inventories and supplies, or settling short-term financial obligations when the need arises. Such a financial situation can impair the ability of a company to take advantage of market conditions or operate on a going concern basis. Financial crisis does not happen overnight, rather  it builds up gradually. The smartest CFOs and finance professionals know how to read between the numbers and take proactive steps to avoid disastrous financial outcome.


    Outlined below are some of the financial and non-financial red flags to watch out for and how to avoid them:

    Financial Red Flags

    (i). Declining Gross Profit Margin

    What this means: Input costs such as raw material, labour, overheads, etc are rising at a faster rate than revenue. When this happens, gross profit will be shrinking.


    Causes: Poor pricing strategy, inefficient production, wastage, and spoilage.


    What to do:

    • Determine product, service, or segment contribution margins to identify the loss-makers
    • Ensure judicious and efficient use of production inputs
    • Reduce overhead costs and avoid wastages without compromising quality.


    (ii). Liquidity Problem

    What this means: This stems from the inability of a company to pay salaries, acquire inventories and supplies, settle short-term financial obligations as they become due.


    Causes: Poor working capital management, economic downturns, poor management oversight, under capitalization (overtrading), market gyrations, economic and political instability, etc.


    What to do:

    • Ensure effective and efficient management of each component of current assets and current liabilities
    • Monitor and control cash flow of receipts and payments
    • Invest surplus funds in short-term marketable securities e.g. treasury bills
    • Strike a balance and design suitable credit terms for your customers
    • Offer trade discount to encourage early settlement
    • Avoid delaying payments to vendors or suppliers
    • Automate invoice processing.


    (iii). Inventory is Increasing Without Sales Growth

    What this means: Inventories are not converted to sales as expected.


    Causes: Poor planning, overproduction, stock obsolescence, low customer demand or patronage.


    What to do:

    • Implement inventory turnover ratio tracking
    • Ensure periodic stock aging reviews
    • Engage in aggressive marketing to improve sales
    • Encourage early payment discounts


    (iv). Increasing Debt and Repayment Problem

    What this means: More borrowing and inability to pay when the need arises. This makes a business susceptible to high interest rates, undue pressure, and potential dilution of ownership structure.


    Causes: Over-reliance on debt financing, declining revenue, high debt-to-equity ratio, poor cash flow management, lender restrictive covenants, macroeconomics factors such as high interest rates.


    What to do:

    • Understand total debt structure, including the principal, coupon rates, maturity dates, restrictive covenants (if any)
    • Perform periodic debt service coverage and gearing ratios
    • Communicate and negotiate debt restructuring early to ease cash flow pressure
    • Prioritize debt repayment to enhance creditworthiness
    • Improve cash flows
    • Engage financial advisor to provide requisite guidance on financial strategy and debt management.


    (v). High Debtors Collection Period

    What this means: Sales are made on credit, but customers are not paying on time, leading to liquidity problem. This increases credit risk.


    Causes: Too liberal credit terms, poor cash flow management, lack of proactive measure to collect receivables.


    What to do:

    • Offer early payment discounts to customers
    • Tighten credit policies
    • Improve collection processes
    • Use the service of a debt factor or debt collection agent
    • Compare your debtor collection period with that of your comparable companies in the industry to set realistic goals.


    (vi). Inaccurate Budget and Forecast

    What this means: This arises when the actual results are different from the budget estimates.


    Causes: Poor financial planning, unrealistic assumptions, and poor budget execution.


    What to do:

    • Ensure financial data are reliable and accurate
    • Thoroughly scrutinize all relevant assumptions to ensure they are realistic
    • Leverage technology to ensure standardization and improve data analysis and key performance indicators
    • Set clear roles, foster collaborative culture, and provide training
    • Regularly monitor actual performance with the budgeted figures and forecast to enhance decision-making.

    Non-Financial Red Flags

    (vii). Low Employee Morale

    What this means: Employee lacks motivation and dissatisfied with work leading to absenteeism, low productivity, and high turnover rates.


    Causes: Ineffective management, lack of recognition, poor rewarding system, lack of growth opportunities, etc.


    What to do:

    • Set clear expectations and goals
    • Gather employee feedback
    • Track HR metrics, link them to financial KPIs, and flag abnormal patterns
    • Encourage open communication
    • Create a positive working atmosphere
    • Pay liveable wages
    • Reward exceptional performance and behaviour
    • Encourage openness and respect for all
    • Promote inclusion and diversity
    • Provide equal opportunity to thrive in the workplace
    • Promote teamwork and collaboration
    • Offer training and opportunities for employees to expand their skills and grow their careers


    (viii). Loss of Confidence

    What this means: Suppliers, customers, and investors are not satisfy with the company’s performance, leading to strained relationships, strict credit terms, lack of patronage, and withdrawal of investments.


    Causes: Poor performance, constant delay in payment, and lack of trust.


    What to do:

    • Monitor credit terms utilization
    • Foster open communication with relevant stakeholders
    • Improve customers satisfaction and experience
    • Build trust and relationship
    • Prioritize key supplier relationships


    (ix). Over-Reliance on Few Clients

    What this means: This is a business risk where significant revenue or profitability of a company depends heavily on few customers. This can have financial repercussions and make a business unduly vulnerable.


    Causes: Lack of, or inadequate marketing and sales efforts, too comfortable with big clients, lack of capacity to serve many clients at once, and weak strategic planning.


    What to do:

    • Build recurring revenue streams
    • Diversify client base
    • Strengthen client relationships
    • Increase marketing and sales efforts
    • Create cash reserves and flexible operations in case of sudden loss of client.


    (x). Weak Corporate Governance

    What this means: This is one of the root causes of financial distress in many organizations.


    Causes: Poor oversight and accountability, board’s risk blindness, corruption and fraud, strategic missteps, erosion of stakeholder confidence, unhealthy company culture, regulatory breaches and penalties.


    What to do:

    • Strengthen the board of directors by appointing competent, independent, and diverse individuals with requisite experience
    • Establish robust internal controls system
    • Foster open communication with relevant stakeholders, including shareholders, employees, regulators, and creditors
    • Develop effective risk management framework
    • Ensure transparency in financial reporting
    • Promote ethical culture and leadership.

    In Summary

    When a company is struggling with operational and financial obligations, or the financial performance of the organization is on a downward trend, or maybe its profitability ratios, including return on capital employed, profit margin, or return on asset are constantly declining, it is a red flag to financial distress. Actions need to be taken quickly to avoid a corporate catastrophic outcome.


    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

  • Business Expenses

    Business Expenses


    Business Expense

    Meaning, Tax Implication, & Practical Examples

    Business Expenses

    These are expenses incurred in the ordinary course of a business. They are expenses a company incurs in running the day to day business activities. These expenses are deducted from the gross profit in arriving at operating profit before interest and tax in a company’s statement of profit or loss. However, it is essential that business expenses are tracked and recorded timely for strategic decision making and to minimise tax liability.


    Business Expense and Tax Deductibility

    Many business expenses are tax allowable deductions. They are recorded as operating expenses in the statement of profit or loss and must be well documented for audit and tax purposes. However, for an expense to qualify for tax deductibility:

    • It must be wholly and reasonably incurred in generating the revenue or income for the period
    • All records and relevant documents, including receipts and invoices attributable to the expenses must be accurately kept
    • Consistent with the Nigeria Tax Act 2025, any expense in which VAT was due but not deducted, or any imported item on which import duty or levy was not charged will not qualify for tax deductions.
    • All private expenses are not tax deductible.
    • Any expenses relating to penalties, fines, bribes, kickbacks, and political contributions are not allowable for tax deductions.

    Categories of Business Expenses

    Basically, business expenses can be categorized into direct costs, indirect costs, and interest costs.


    Direct expenses

    These are costs that are directly attributable to producing a product or service. Direct costs vary in proportion to production volume. This means that the higher the unit produced, the higher the direct costs that will be incurred. Examples include direct materials and components, direct labour, manufacturing supplies, etc. The direct costs are deducted from the revenue in arriving at gross profit.


    Indirect Expenses

    These are overheads incurred in running the business activities. Indirect costs are not directly related to producing a product or service. Examples include office or factory rent, salaries, marketing and advertising, depreciation, utilities, etc. Operating costs are usually deducted from the gross profit in the determination of operating profit before interest and tax.


    Interest Costs

    These are costs arising from debt, loans, borrowing, or financing activities. Examples include interest on bank loan and overdraft, interest on lease, interest on debt or borrowing.


    Common Examples of Business Expenses

    The following are some of the examples of business expense:


    1. Wages and Salaries
    2. Rent
    3. Utilities
    4. Marketing & Advertising
    5. Staff Training
    6. Meals & Entertainment
    7. Insurance
    8. Bank Charges
    9. Supplies
    10. Maintenance and Repairs
    11. Depreciation
    12. Professional Fee
    13. Dues and Subscriptions
    14. Gifts & Donations


    Let’s explore each line item in detail:


    Wages and Salaries

    These are payments to workers, employees, and other staff during the month under consideration, for their effort to ensure business continuity. They represent the compensation paid to workers or staff for the services rendered to a company or employer. Generally, wages and salaries account for significant amount of operating expenses. Wages differ from salaries and their key difference are stated below:


    Difference Between Wages and Salaries

    The key differences between wages and salaries can be explained as follows:


    • Basis of Payment: Wages are paid hourly, daily, weekly, or piece-rate. On the flip side, salaries are paid monthly
    • Stability: Wages payment is less stable and it fluctuates, depending on the number of hours worked. Salaries are more stable and based on fixed payment structure.
    • Overtime Pay: Wages are eligible for overtime pay. Salaries on the other hand, may or may be eligible depending on the organizational policy.
    • Job Type: Wages are suitable for manual, casual, skilled, and unskilled labour. Salaries are mostly appropriate for professionals and administrative workers.
    • Fluctuation: Wages paid to workers vary or fluctuate depending on the number of hours worked or units produced. Whereas the salaries paid to workers or employees are fixed in nature i.e. it does not fluctuate.
    • Accounting Classification: In financial accounting, wages are classified as cost of sales as a deduction from revenue in arriving at gross profit, if it relates to production. Whereas salaries are generally classified under operating expenses in determining operating profit before interest and tax. In addition, for the purpose of cost accounting, direct wages are regarded as prime cost of production, while salaries are treated as factory overheads or administrative expenses.


    Rent

    This represents the consideration paid to a landlord or property owner by a tenant for the use of an asset, including land, building, or property for a specified period. The consideration or fixed periodic payment gives the tenant the right to use or occupy the property. Generally, rent is paid monthly, biannually, or annually, depending on the agreement between the parties (i.e. landlord and tenant).


    Key Characteristics of a Rent

    • Contract Based: It is governed by a lease or rental agreement. The contractual agreement will expressly state the responsibilities of both parties on the property.
    • Ownership: The tenant does not own the property, only has the right of usage.
    • Frequency of Payment: Rent is paid periodically, e.g. monthly, quarterly, biannually, yearly.
    • Payment: Rent is a fixed periodic payment or can be reviewed depending on the contractual agreement.
    • Accounting Treatment: A tenant or lessee will treat rent as an expense, while the landlord will record as an income in the statement of profit or loss.


    Types of Rent

    • Office Rent: This is paid for the use of office space or premises
    • Factory Rent: Amount paid for the use of factory building or warehouse
    • Residential Rent: Payment by an individual to a landlord to live in a house or apartment
    • Equipment Rent: This is paid for using tools, machinery, plant, or equipment own by a third party
    • Land Rent: Paid for the land used for agricultural or commercial purposes


    Utilities

    These are expenses incurred for basic essential services required for running a business, including electricity, water, gas, waste disposal, heating, cleaning, internet, telephone, etc.


    Common Types of Utility Expenses

    • Electricity: To power computers, machines, and provide lightening
    • Water: Required for general cleaning activities and washing
    • Gas: For heating or powering certain equipment
    • Internet & Telephone: For communication and data usage
    • Waste Disposal: For trash removal and sanitation services


    Marketing & Advertising

    These are expenses incurred by a business for the purpose of promoting a product or service, attract new customers, generate revenue, and build brand awareness. These expenses are essential to ensure business growth, continuity, and market competitiveness.


    Components of Marketing and Advertising Expenses

    • Digital Advertising: Social media ads (e.g. Facebook, Instagram, LinkedIn), Google ads, YouTube ads.
    • Traditional Advertising: Paid ads on TV, radio, newspapers, magazines, billboards.
    • Promotional Materials: For printing flyers, banners, brochures, branded merchandise.
    • Events & Sponsorships: For exhibitions, trade shows, product launches, brand sponsorships.
    • Marketing Staff Costs: Salaries of marketing department staff, or cost paid to consultants, or freelancers.
    • Content Creation: For graphic designs, copywriting, photography, video production, etc.
    • Website & SEO: For website design, website management, SEO tools, email marketing, blog content, etc.
    • Public Relations: Influencer partnerships, media outreach, press releases.


    Staff Training

    This refers to the expenses incurred by a business to enhance employees’ skills, knowledge, and performance through formal or informal learning programs. It is designed primarily to maximize or boost business productivity, efficiency, and ensure employee satisfaction.


    Components of Staff Training Costs

    In practice, training costs may include:


    • External Training Fees: These are fees paid to training organizations, consultants, or online courses
    • In-house Training Expenses: These are expenses incurred for venue setup, training materials, or meals.
    • Travel & Accommodation: Offsite training expenses incurred on transport, lodging, and meals.
    • Software & Tools: For e-learning platforms, licenses, etc.
    • Certifications & Exams: Payment for registration, tuition, and professional exams such as ICAN, ANAN, ACCA, CIMA, etc.


    Meals & Entertainment

    These are expenses incurred by a business on food, drinks, and business related recreational activities, including client meetings, staff events, or networking activities. It should be noted that not all meals and entertainment are allowed for tax deductions. For this purpose, good record keeping and documentation should be maintained. Auditors may want to know who, why, when, how much, and the approval.


    Components of Meals & Entertainment

    • Client Meals: Lunch or dinner meetings with clients or prospects
    • Staff Meals: Staff lunch, meals during overtime, staff meetings, or training sessions
    • Business Events: Company retreats, end of the year party, product launch events, appreciation parties
    • Refreshments: Snacks, tea, or coffee for meetings
    • Entertainment Activities: Tickets for sporting events, shows, concerts for clients or business.


    Important Notice for Tax and Audit Purposes

    • Meals and entertainment must be business-related to qualify for tax deductions
    • Personal and extravagant spending is not allowed as business expense
    • The expenses incurred must be well documented. The receipts, purpose, and list of attendees should be provided for audit and tax purposes.


    Insurance

    This relates to premium paid by a business to an insurer for protection against specific risk or financial losses. It indemnifies the business against unexpected future events arising from fire, accidents, theft, or liability claims.


    Types of Business Insurance

    • Property Insurance: This covers loss or damage to buildings, equipment, inventory
    • Health Insurance: Medical coverage for employees
    • Life Insurance: Provides benefits to beneficiaries upon an employee’s death
    • Liability Insurance: Covers legal claims for injury or damage caused by the business to a third party
    • Professional Indemnity: This protects against claims of professional negligence


    Bank Charges

    These are expenses arising from financial transactions with banks. They are fees and commissions deducted by a bank from the account of a business for using its financial services. Bank charges must be reconciled regularly during bank reconciliations to ensure that bank statement and cashbook align.


    Common Types of Bank Charges

    • Account Maintenance Fees: Monthly or annual fee for running the account
    • Card Fees: Annual debit/ credit card maintenance charges
    • Transaction Fees: Charges for transfers, withdrawals, deposits, or cheque clearing
    • ATM Fees: Charges paid for using ATMs, especially from other banks
    • Loan Processing Fees: Cost incurred for setting up or managing loans
    • Foreign Exchange Fees: Charges incurred when conducting international transactions
    • SMS/ Alert Charges: Charges for transaction alerts via SMS or email


    Supplies

    These are consumable items used by a business in running the daily business operations. Generally, supplies are not required for sales but used in the day to day business activities. Examples include:


    • Office Supplies such as paper, pens, files, printer ink, envelopes
    • Cleaning Supplies, including soap, detergent, disinfectants, mops, brooms, buckets
    • Production Supplies like lubricants, gloves, rags
    • Canteen Supplies, including cups, spoons, disposable plates, tea, sugar.


    Maintenance and Repairs

    These are expenses incurred in ensuring that assets such as buildings, equipment, machinery, and vehicles are in good working condition. These expenses help in ensuring smooth business operations and extend the economic useful life of assets without materially enhancing their value or capacity. Examples include:


    • Building Maintenance e.g. painting, plumbing repairs, AC servicing, lighting fixes
    • Equipment Servicing, including generator servicing, fixing production machinery, calibrating tools
    • Vehicle Repairs, such as servicing, tyre replacement, brake repairs for company vehicles
    • IT Maintenance e.g. updating software, fixing computers, replacing parts.


    Depreciation

    This represents a reduction in the value of an asset over a given period arising from wear and tear, usage, or obsolescence. It is a systematic allocation of the cost of a tangible asset, including building, motor vehicle, equipment, etc over its economic useful life, using straight-line, reducing balance, or units of production methods. Depreciation is non-cash operating expense and reduces the book value of the non-current asset in the statement of financial position.


    Professional Fee

    This represents the payment made to an external expert or professional, including accountant, lawyer, IT specialist, engineer, architect, etc. for the services rendered to the business. The fee is a compensation to the professionals for their time, knowledge, expertise, and value they provided to the business. Professional fee should be properly documented to ensure compliance, transparency, and for tax purposes.


    Dues and Subscriptions

    These are fees paid by a business to professional bodies, industry associations, or publications to validate memberships, access resources, or receive services. Examples of due and subscription include:


    • Professional Memberships: ICAN, ACCA, ANAN, NSE, NBA annual membership fees
    • Industry Associations: Clubs, business chamber memberships, trade groups, regulatory bodies
    • Publication Subscriptions: Business journals, magazines, online news sites
    • Software Subscriptions: Accounting software (e.g., QuickBooks, Sage), research tools
    • Online Platforms: Training platforms such as Coursera, Udemy, LinkedIn Learning


    Gifts & Donations

    These are expenses incurred by a business for voluntary transfer of money or property without expecting anything of value in return. Usually, gifts and donations are given to employees, clients, communities, charities, or nonprofit organisations for the purpose of building goodwill, support social causes, or enhance relationships. Examples of gifts and donations include:


    • Employee giftsg. birthday gifts, retirement tokens, service awards
    • Corporate gifts such as hampers, branded souvenirs, or end-of-year gifts for clients or employees
    • Charitable donations, including contributions to schools, NGOs, religious bodies
    • Community Support such as scholarships, donations to local projects, disaster relief funds.


    Important Notice for Tax and Audit Purposes

    • The amount must be reasonable and well documented
    • Donations must be made to approved charitable organizations or bodies for tax purposes
    • Gifts to individuals, including employees, clients are not allowable tax deduction

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

  • Overtrading: How Rapid Growth Can Impair Liquidity

    Overtrading: How Rapid Growth Can Impair Liquidity

    Overtrading

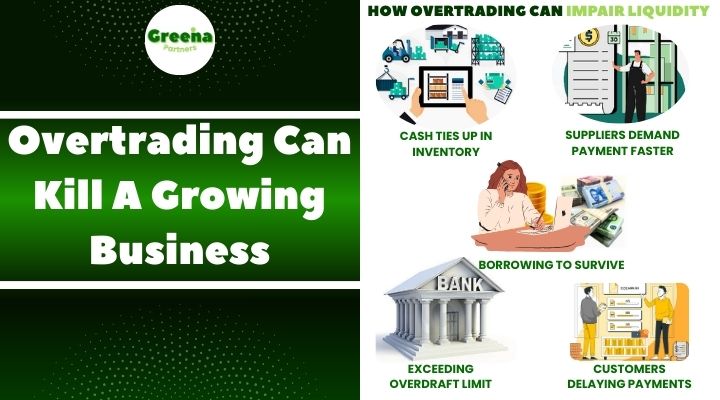
    Overtrading Can Kill A Growing Business

    Overtrading, also known as undercapitalization, occurs when a company is trying to undertake a larger volume of trade or activities than it has financial capacity to do. A company is said to be overtrading when it grows rapidly than its cash flow can support. This can have serious financial repercussion for the business.

    Though, sales are booming; orders are flying in… It sounds good, but your bank account says otherwise. The business operations may be disrupted if your bank refuses to grant credit facilities or your major supplier insists you pay on cash.

    How Overtrading Can Impair Liquidity

    1. Inventory grows faster than cash
    • To satisfy customer demands, you acquire more inventories.
    • The inventory swallows up cash, and until sold and cash is received, liquidity suffers.


    1. Customers delay payments
    • Sales increase, but customers don’t pay on time and as a result, liquidity is trapped.
    • The book says the company is rich (on paper), but in reality, it is broke in the bank.


    1. Suppliers want their payments faster
    • Cash position will suffer if the number of days credit is taken from suppliers is shorter than the days credit is given to customers.
    • The shorter the gap, the more company will be under pressure to settle supplier.


    1. Borrowing to survive
    • Despite increased sales, you may borrow loan to pay salaries, rent, or acquire raw materials.
    • Borrowing increases interest costs, and worsening liquidity position.


    1. Exceeding overdraft facilities limit
    • Sales grows. Need cash to purchase inventory. You constantly exceed overdraft facilities limit agreed with the banks.
    • The business operations may be curtailed, if the bank facility is withdrawn.


    Warning Signs Your Business is Overtrading

    • Creditor payment period getting longer i.e. you are delaying payments to suppliers
    • Rapid growth in turnover, cash is constantly tight
    • Always borrowing to fund daily business activities
    • Struggling to satisfy customer demands or orders efficiently
    • Low liquidity ratio
    • Cash operating cycle is increasing.


    How To Prevent Overtrading

    • Ensure judicious and efficient management of working capital
    • Improve your cash flow projection
    • Avoid over-investment in inventory
    • Negotiate better credit terms with the suppliers
    • Shorten debtors collection period i.e. tighten your credit terms
    • Scale consistent with your working capital capacity
    • Avoid unnecessary debt
    • Seek professional advice.

    In Summary

    Growth is great and sweet. But uncontrolled growth without working capital will lead to liquidity problem. In addition, failure to meet customer demands can lead to strained relationships with customers, vendors, or even employees, eroding the business reputation and impair its ability to take advantage of market conditions.

    Hence, effective and efficient management of the working capital investment is essential to maintaining and ensuring business continuity. Engage financial advisors to develop strategies for managing growth and preventing overtrading.

    NEED EXPERT SUPPORT?

    At Greena Partners, we help businesses like yours grow sustainably- with clear financial systems, robust cash flow planning, and actionable advisory support. Our team can collaborate with you to develop strategies to managing your working capital judiciously.


    Let’s talk.👉 Contact us today to schedule a consultation.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

  • Cash Flow vs Profitability: Key Difference

    Cash Flow vs Profitability: Key Difference

    Cash Flow vs Profitability

    Cash Flow vs Profitability: Key Difference

    In strategic financial management, cash flow and profitability are two pivotal concepts that often get confused. Though, they serve different purposes, both are mutually dependent, but must be managed judiciously to achieve a company’s long-term success. Understanding their clear distinctions and interdependence can help companies, investors, or business owners make informed financial decisions and ensure sustainability.

    What is Profitability?

    Profitability measures the ability of a company to generate profit after deducting all cash outflows(expenses) from revenue. It is represented in three (3) forms, including:


    • Gross Profit: Revenue minus the cost of goods sold (COGS)
    • Operating Profit: Gross profit minus operating expenses (OPEX)
    • Net Profit: The final profit available for distribution after deducting all expenses, including taxes and interest.


    Profitability is a key indicator of a company’s financial performance and long-term viability. However, it does not show that a company is liquid to meet short-term financial obligations when they become payable.


    What is Cash Flow?

    Cash flow refers to the actual receipts and payments generated by a business in a period. It represents the movement of money into and out of a business. For instance, when a company sold goods to customers, cash flows into the business and when the company pays staff salaries, cash flows out of the business. It is usually grouped into:


    • Operating Cash Flow: Cash generated from ordinary activities of the business.
    • Investing Cash Flow: Cash paid to acquire non-current assets or received from disposal of assets.
    • Financing Cash Flow: Cash related to borrowing, debt repayment, or dividend payments.


    A company can be profitable in theory but still experience cash flow problems if cash is tied up in receivables or inventory.

    Key Differences Between Cash Flow and Profitability

    Cash Flow vs Profitability

    Why Both Matter for Business Success


    A Profitable Business Can Liquidate Due to Cash Flow Problems
    Many profitable companies collapsed due to lack of working capital to cover business operating expenses such as salaries, rent, payment to suppliers, or settlement of short-term debt obligations. Hence, poor cash flow management can lead to insolvency.


    Strong Cash Flow Position Enables Growth and Flexibility
    A strong cash flow position will enable a company to invest surplus funds in short-term marketable securities, expand, reinvest in operations, and undertake new opportunities, even though the business is not highly profitable yet.


    Financial Metrics for Investors and Lenders
    While investors look at profitability to measure a company’s long-term potential, lenders assess cash flow to determine the business’s ability to settle debt obligations.


    Strategic Decision-Making Requires Balance
    Maintaining balance between profitability and cash flow is essential to achieving a business success. A company that focuses only on profitability and neglect cash flow, may experience liquidity problems. On the flip side, prioritizing cash flow without ensuring profitability can deny the business the opportunity to attract the right investments.


    How to Manage Cash Flow and Profitability Effectively

    • Monitor Cash Flow Regularly: Ensure accurate forecasting and use cash flow statements to anticipate shortages.
    • Optimize Receivables and Payables: Encourage early settlement discount from customers and negotiate better payment terms with suppliers.
    • Cost Optimization: Identify and manage costs efficiently. Avoid unnecessary expenses.
    • Balance Growth and Liquidity: Invest strategically without compromising cash reserves.
    • Leverage Technology: Integrate accounting software to automate financial processes, track cash flow, and generate reports.
    • Inventory Management: Optimize inventory levels to avoid over/under stocking of materials, avoid stock-out and wastage, and improve efficiency. You can also adopt just-in-time system (JIT) so that you request for inventory only when it is needed.
    • Marketable Securities: Invest surplus funds in short-term marketable securities like treasury bill, commercial papers, bankers acceptance, etc.


    In Summary

    Both cash flow and profitability are essential for business survival and success. A company needs profits to sustain operations in the long run but also requires healthy cash flow to keep running smoothly. Striking the right balance between the two financial metrics ensures stability, growth, and resilience in an ever-changing business environment.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business
  • 7 Common Accounting Mistakes SMEs Make & How to Prevent Them

    7 Common Accounting Mistakes SMEs Make & How to Prevent Them

    7 Common Accounting Mistakes

    7 Common Accounting Mistakes SMEs Make & Strategies to Prevent Them

    Businesses inevitably make mistakes, but what sets a well-managed company apart is its ability to recognize, address, and learn from those errors. Accounting, like every other aspect of business operations, is prone to mistakes- some of which can lead to significant financial losses, reputational damage, or even threaten the company’s going concern.

    For small and medium-sized enterprises (SMEs), accounting errors can be particularly costly, as they often operate with limited financial buffers. From misclassifying expenses to poor record-keeping and non-compliance with tax regulations, these mistakes can disrupt cash flow, hinder growth, and attract regulatory penalties.

    To help business owners and financial managers maintain sound financial health, we highlight seven common accounting mistakes SMEs frequently make and provide practical strategies to prevent them.

    Improper Record Keeping

    Tracking your finances will be difficult without accurate record keeping of accounting transactions. Lack of proper documentation can lead you to trouble during audit or tax season. To avoid losing money, ensure your documents and other accounting records are properly organized, use accounting software, or hire a professional accountant to help you.


    Mixing Personal & Business Finances

    Don’t mix your personal finances with that of the business. Instead, open a separate business account to accurately track receipts and payments.


    Failure to Reconcile Bank Statements

    This is a recipe for fraud, undetected errors, and inaccurate reporting. It can adversely impair decision-making and compliance. Regularly reconcile your books with the bank statements can help detect errors and fraud timely, and ensure data validation and accounting accuracy.


    Lack of Cash Monitoring & Controlling

    Profitability is different from liquidity. A company might be profitable but not liquid to settle short-term financial obligations. Lack of proper monitoring and controlling of receipts and payments will impair the ability of the business to take advantage of market condition. To avoid this, cash budget and projection should be prepared annually. The underlying receipts and payments must be closely monitored to keep the business afloat.


    Ignoring Tax Obligations

    Being tax compliant is as essential as maximising profit to enhance shareholders value. Avoiding tax obligations, including late filings of returns can lead to penalties. Instead, stay updated on tax deadlines and compliance requirements.


    Lack of Data Backup

    This can potentially lead to financial losses, reputational damage, permanent data loss, cyberattacks, operational disruptions, or legal and compliance issues, which can adversely impact business operations. To backup your business data, you can utilize external hard drives or cloud storage services, including Google Drive.


    Failure to Engage a Professional Accountant

    Accurate bookkeeping is essential for your business, and only a chartered accountant can ensure it is done correctly and in compliance with financial standards. Handling your accounting and bookkeeping yourself or hiring an unqualified person to cut costs can lead to serious financial repercussion and reputational damage. A professional accountant ensures accuracy, compliance, and strategic financial planning to help grow your business profitably.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

  • Managers Participation In Budget Setting: Downside Effects & Mitigating Strategies

    Managers Participation In Budget Setting: Downside Effects & Mitigating Strategies

    Managers Participation

    Managers Participation In Budget Setting: Downside Effects & Mitigating Strategies

    Managers participation in the budget setting process is designed principally to enhance organizational performance and promote a sense of ownership, commitment, and motivation. This is because when managers participate actively in budget preparation, they are more likely to converge their individual departmental goals with the overall corporate strategy, leading to optimal resource allocation, efficiency, and accountability. In addition, when managers participate in budgeting process, they feel valued and empowered, and this will, in effect, enhance their morale.

    However, in some certain situations, the involvement of managers in budget setting can have downside effects on the organization, leading to poor budget performance. Below are some of the circumstances where managers participation in budgetary process can have negative repercussions:

    Conflict of Interest

    Managers may prioritize their department’s interests over the organization’s overall goals. Oftentimes, managers may want to maximize the resources of their departments to avoid shortages and may not fully understand or be aware of the company overall financial constraints. This can cause resource hoarding, inter-departmental conflict, and misalignment with the strategic objectives. Due to conflict of interest, some departments may be overfunded while others may be underfunded or scrambling for funds.


    Excessive Time and Effort

    Budgeting activities can be cumbersome and time-consuming, shifting attention of people from the principal operational tasks. Too much of managerial time is expended on budget meetings, resulting in low productivity. So, when too many managers are involved in the budgeting process, organizational politics, as well as long debates and disagreements, can slow down decision making, giving rise to delay in budget approvals.


    Resistance to Change

    Managers that are already accustomed to traditional budgeting methods may resist innovative or strategic budgeting approaches such as zero-based budgeting (ZBB) or activity-based budgeting (ABB) during participation. This can limit the ability of the company to adapt to changing circumstances or implement improvements. Resistance to change arises due to lack of understanding of the new budgeting techniques, including lack of trust, fear of uncertainty, perceived loss of control over budgets. This has the potential to stifle innovation, create inefficiencies, and can lead to conflict between senior management and operational managers.


    Budgetary Slack Creation

    Managers may deliberately understate or overstate budget estimates of receipts and payments to make budget targets easier to achieve. This can impair organizational performance, leading to suboptimal allocation of resources, including money, time, materials, and labour. Inefficient resource allocation can adversely impact the quality of jobs, products, or service, delay in project completion, leading to increased costs. Managers are incentivized to create budget slack, especially where performance evaluation is based on budget variances, or where bonuses are attached to budget performance.

    The creation of budgetary slack can be avoided or minimised by ensuring that incentives or any performance measure is consistent with the organizational goals. In addition, companies can implement a transparent budgeting process and ensure budget estimates are realistic. Actual spend and budget estimates, including forecast, should be closely monitored and any resulting variance should be promptly addressed.


    Lack of Competence in Budget Setting

    Financial, analytical, and strategic skills are essential to making a good budget. If managers lack the requisite skills, knowledge, or experience to contribute effectively to the budgeting process, they may set unrealistic or suboptimal budget targets. This can lead to overspending, financial instability, inefficiencies, poor financial control, or missed opportunities. Some managers may have operational knowledge of the business but lack the financial expertise to fully understand the cost structures, cash flow projections, and or risk factors.

    Managers’ lack of competence may affect budget performance, resulting in frequent budget revision due to poor planning, misallocation of resources, and setting unrealistic budget targets.


    Opportunistic Behaviour

    This involves the action taken by some individuals or groups, when setting budget, to maximize their own self-interest at the expense of the organizational goal. This happens when managers manipulate the budget estimates to secure personal benefits or incentives, especially those tied to budget performance. This undermines organizational goals and reduces overall accountability. Managers can deliberately overestimate expenses or underestimate revenues to create a buffer for future spending or to make it easier to achieve budget targets.

    To minimize or avoid opportunistic tendency, company can develop mitigating strategies, by providing strong leadership, ensuring transparency in budget process, set clear budget performance metrics, and ensuring goal congruence among departmental managers.


    Unrealistic Expectations

    Setting unrealistic budget expectations can lead to disappointment, financial strain, and even failure to achieve goals. If managers set aggressive  revenue or cost-cutting targets that are unattainable, it may lead to overly optimistic budgets. This can then lead to missed targets, create undue pressure for employees, erode credibility and morale, and frequently adjusting budget estimates to align with the prevailing market conditions.

    Mitigating Strategies

    The following are some of the strategies that can be employed by organizations to mitigate the adverse effect of managers participation in budget setting process, including:

    • balance participative budgeting with oversight mechanisms
    • Set clear budget guidelines to prevent budgetary slack and manipulation
    • Provide financial training to managers and other employees to improve budgeting skills
    • Implement checks and balances to ensure accountability
    • Balance participation with efficiency to avoid excessive delays
    • Encourage critical evaluation rather than groupthink
    • Carefully track income and expenses to gain insight on the prevailing financial condition
    • Set aside funds for unexpected expenses to avoid overspending and maintain financial stability
    • Ensure clear and open communication about expectations and potential challenges.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

  • Transfer Pricing by Multinational

    Transfer Pricing by Multinational

    Greener Partners

    Multinational Transfer Pricing

    Transfer pricing is the monetary value attached to the goods or services exchanged between divisions or subsidiaries under common control. Whereas the international transfer pricing represents the pricing of goods, services, and intangibles between connected parties in an organization across international boundaries. It is a strategy usually adopted by companies especially multinationals, to redistribute resources between the parent and subsidiaries or affiliates to reduce tax burden.


    Transfer pricing is an essential consideration for multinational entities when conducting transactions between parent and subsidiaries located in different countries. Transfer pricing provides many benefits to companies, particularly those with foreign operations.


    Oftentimes, companies manipulate or falsify records to avoid taxes. In some cases, companies can lower their costs when transacting with connected parties to avoid tariff on goods and services exchanged. The relevant tax authorities are aware of these sharp practices by companies and that is why their records are usually subjected to thorough scrutiny.

    Significance of International Transfer Pricing

    Some importance of international transfer pricing include:


    Tax Optimization

    Generally, transfer pricing affects the distribution of income between countries, and this usually impact the global tax burden of the multinationals. However, complying with the transfer pricing regulations can help companies to minimize the risk of double taxation and optimize tax burden.


    Regulatory Compliance

    To prevent tax base erosion and profit shifting (BEPS), including the need to ensure that transfer pricing is fairly determined to reflect the market price, regulatory authorities around the world and Organisation for Economic Co-operation and Development (OECD) have specific rules and regulations in which multinationals must complied with. Complying with these specific rules and regulations can make companies avoid compliance risk.


    Profit Allocation

    Transfer pricing is used for resource allocation between connected entities involving international transactions. This usually determines the profit attributable to the multinational, and in effect, its financial performance.


    Key Components of International Transfer Pricing

    Basically, the international transfer pricing usually involves:


    Goods

    This represents transfer of physical products between connected parties having a common control i.e., within an organization.


    Services

    This involves managerial, technical, and administrative services exchanged between the parent and its subsidiaries, or affiliates.


    Intercompany Loans and Advances

    This relates to financial arrangements between the parent company and its subsidiaries.


    Intangibles

    These include intellectual property, trademarks, patents, franchise, and brand values exchanged between the parent and its subsidiaries.


    Methods of Transfer Pricing

    Consistent with the dictate of (OECD), the following are major transfer pricing methods, including:


    Comparable Uncontrolled Price (CUP) Method

    This represents one of the most popular transfer pricing methods in the determination of arm’s length prices to be used between connected parties. This method compares the price charged between related parties for goods or services in a comparable uncontrolled transaction. The CUP method is generally used in arm’s length principle where sufficient data is available. It is easy to apply and mostly preferred by many tax authorities.


    Resale Price Method

    Under this method, the transfer price to be used between related parties is the resale price to an independent entity less gross profit margin for the goods purchased from a connected party for resale.


    Cost Plus Method

    Consistent with the arm’s length principle, transfer price is determined by adding an appropriate markup to the total cost incurred on the supply of goods or service in a related party transaction.


    Transactional Net Margin Method

    This involves comparing the net profit margin in a controllable transaction with the net profit margin in comparable uncontrolled transaction. It examines the net profit margin relative to an appropriate base involving assets, sales, and costs, that a taxpayer earns from a controlled transaction.


    Profit Split Method

    This method identifies the combined operating profit or loss to be allocated between related parties in a controlled transaction, by referencing the value contributed by each participant to earn the profit.


    Regulatory Framework

    The Organisation for Economic Co-operation and Development (OECD) provides detailed guidelines on transfer pricing. The guidelines emphasized the need to utilize the principle of arm’s length transaction between connected parties. This principle ensures that transactions between related companies are valued at market prices.

    OECD also provides initiative through BEPS to address the tax avoidance scheme usually adopted by entities to exploit loopholes and mismatches in tax regulations between countries. This ensures that transfer pricing aligns with the value creation system, and that there is transparency in country-by-country reporting (CbCR).

    In addition, local tax authorities have specific rules and regulations that govern transfer pricing. In Nigeria, transfer pricing is regulated by the existing tax laws, including Income Tax (Transfer Pricing) Regulations 2018.


    Challenges and Considerations

    There are plethora of issues facing transfer pricing practices, and some of which include:

    Documentation: Transfer pricing transactions requires detailed documentation to support the judgment and policies adopted, especially during tax audits. These documents are usually subjected to thorough investigation to ensure that the right tax is paid.

    Complexity: Generally, transfer pricing involves multiple jurisdictions with specific rules, regulations, and interpretations. Therefore, the ability to navigate through all these can pose a daunting task.

    Disputes: Oftentimes, transfer pricing can lead to disputes between tax authorities of different jurisdictions, resulting to double taxation or litigation.

    Risk Management: Having the right expertise to develop robust transfer pricing policies to manage compliance, financial, and reputational risks can be challenging.

    Economic Changes: The prevailing market conditions, exchange gyrations, and unstable economic environments can have far-reaching effect on the transfer pricing strategies.


    Best Practices

    The following are some of the transfer pricing best practices that can be adopted by companies:

    Documentation: Companies should maintain up to date and detailed documentation to support transfer pricing policies and practices.

    Review: The transfer pricing policies should be regularly reviewed to reflect the prevailing market conditions and regulatory changes.

    Benchmarking: The transfer pricing policies and decisions should be consistent with the industry standard and that of the comparable companies.

    Professional Expertise: Companies should engage professionals endowed with transfer pricing expertise to help navigate tax intricacies and international regulations.

    Advanced Pricing Agreement: Align or enter into agreement with the relevant tax authorities to obtain certainty on transfer pricing methods to avoid future disputes.


    Ethical Issues in Transfer Pricing

    Transfer pricing often involves ethical issues that bother around abuse and manipulation of records by multinational enterprises (MNEs), and which can negatively impact the economic and social welfare of a country. Some of the key ethical issues include:

    • Tax Avoidance and Evasion
    • Economic Inequality
    • Fairness and Equity
    • Transparency and Accountability
    • Corporate Social Responsibility
    • Legal and Regulatory Challenges


    Tax Avoidance and Evasion

    Companies can manipulate transfer prices to achieve a targeted goal. For instance, multinationals can use transfer pricing to shift profits from countries with high tax rate to jurisdictions with lower tax rate to reduce their overall tax burden. This practice may seem legal, but it deprives countries of their benefits from tax revenue. In addition, when multinationals allocate profits to jurisdictions with favourable tax rates (i.e., tax havens), there will be tax base erosion in the countries where significant economic activities occur, thereby limiting their ability to fund public projects.


    Economic Inequality

    Shifting profits from countries with higher tax rates to tax havens can worsen economic inequality of the countries because resources available to fund social programs, infrastructure, and public services may be inadequate. Also, developing countries who often rely heavily on tax revenues can be disproportionately impacted by aggressive transfer pricing practices, impairing their ability to reduce poverty and develop as a nation.


    Fairness and Equity

    There is huge disparity between SMEs and MNEs, since the SMEs do not have the requisite resources to engage in sophisticated transfer pricing strategies, resulting in an uneven playing ground. Also, local businesses may face higher effective tax rates relative to companies that engage in international transfer pricing, which give undue advantage to MNEs over the local companies.


    Transparency and Accountability

    Companies can intentionally make transfer pricing practices to be opaque and complex in order to make it difficult for relevant tax authorities to understand and scrutinize the financial records of the MNEs. At times, lack of, or inadequate disclosures in financial reporting and intercompany transactions can limit the ability of the tax authorities to hold MNEs accountable for their transfer pricing practices.


    Corporate Social Responsibility (CSR)

    In addition to legal compliance, ethical business practices encompass honesty, fairness, and positive contribution towards to the society. Engaging in aggressive transfer pricing practices can undermine the CSR efforts of MNEs and impair their reputation.


    Legal and Regulatory Challenges

    MNEs usually exploit gaps and mismatches in different tax jurisdictions in relation to transfer pricing. As a result, enforcing compliance may be challenging. Also, ethical issue can occur when MNEs encounter double taxation due to tax disputes between tax authorities of different jurisdictions, resulting in lawsuits and strained international relations.

    In Summary

    International transfer pricing is a challenging but essential aspect of multinational operations. It requires careful consideration, detailed documentation, and strategic planning to maximize tax gains and ensure compliance. Transfer pricing practices are used by the MNEs to deprive home country of their benefit of tax revenue through Base Erosion and Profit Sharing (BEPS). The OECD and local tax authorities have enacted regulations to prevent the abuse and manipulation arising from BEPS and other activities. Complying with these regulations will help companies to minimize double taxation and compliance risks.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos

  • Financial Statement Fraud

    Financial Statement Fraud

    Greena Partners

    Financial Statement Fraud

    Financial statement fraud occurs when a company intentionally manipulates financial information to deceive or mislead shareholders, investors, lenders, and other users of the general purpose financial statements.

    Aggressive accounting, that is, choices that are designed by management to enhance a company’s financial performance and position, by inflating revenue, earnings, and other reported operating cash flows, or by decreasing the amount of expenses or debts in a reporting period, can threatened the going concern of a business if not nip in the bud.

    This kind of fraud can have severe consequences for organizations, leading to damaged reputation, financial losses, and even legal repercussions. Understanding common methods of financial statement fraud, as well as implementing effective detection and prevention measures, is crucial for maintaining the integrity of financial reporting.

    There are several methods usually employed by companies to commit financial statement fraud. Some of which are set out below:

    1. Revenue Manipulation
    2. Overstating/ Understating Expenses
    3. Improper Asset Valuation
    4. Concealing Liabilities
    5. Fraudulent Disclosures
    6. Round-Tripping
    7. Related Party Transactions
    8. Timing Differences
    9. Manipulating Reserves and Accruals
    10. Corruption

    Revenue Manipulation

    Companies undertake several methods of perpetrating revenue fraud. Revenue can be artificially inflated by recording sales that have not been earned or recognising revenue prematurely. A fictitious trade receivable can be manufactured to create artificial sales. At times, companies inflate trade receivables in order to increase revenue. In addition, companies can record fictitious sales, or record revenue when risk and reward incident to the goods or services have not been transferred to the customers.


    Overstating/ Understating Expenses

    Expenses can be manipulated to achieve a predetermined objective. Management can increase expenses arbitrarily in order to reduce the company’s tax liabilities. For example, directors’ remuneration, marketing expenses, etc., can be inflated to achieve a lower profit, and in effect, resulting in a lower tax been paid. On the flip side, management can intentionally understate expenses by undercharging depreciation or any other specific expense line items to achieve high profit margin to mislead investors. Other methods include to defer legitimate expense to the next reporting period, capitalizing expenses, etc., all in a bid to increase reported profit.

    Generally, companies engage in creative or gymnastic accounting practices by cooking or making their books appear so rosy than necessary to deceive investors. Though, the tax authorities are aware of these sharp practices, and that is why a company’s audited financial statements is being subjected to thorough scrutiny during tax audit.


    Improper Asset Valuation

    The valuation of assets in the statement of financial position can be materially manipulated to achieve intended results. Assets such as properties, plant, and equipment, goodwill, including inventories can be overvalued to misrepresent the company’s  financial position. For instance, when inventories are overvalued, the reported profit will be lower, and in effect, a lower tax liability will be paid. Misleading asset valuation can also arise when a company intentionally fails to write down impaired assets to their recoverable amount in consonant with the dictate of IAS 36 on impairment of assets.


    Concealing Liabilities

    Companies can omit or understate liabilities in order to present a healthier financial position in a particular period than they actually have. Concealing liabilities can arise when an entity’s management fail to disclose off-balance sheet items including operating leases or contingent liabilities. It can also occur when account payables are understated, or improper recording of warranty costs and loan covenants are carried out in the books.

    At times, companies’ management can use “big bath” technique to manage their earnings by conducting a one-time write-offs in a reporting period to enhance future profit. Big bath is an unethical behaviour usually carried out by a company’s top level management when they realised that they cannot achieve the minimum earnings target in a given period. The management can then delay revenue realization, create big write-offs, or making prepay expenses in order to get big bonuses in the near future.


    Fraudulent Disclosures

    The information provided in the financial statements must be accurate, faithfully represented, and devoid of any ambiguity to enable users make informed business and investing decisions. Fraudulent disclosures involves intentional manipulation of facts by providing misleading or false information in the financial statements. Companies can omit material information, making overly optimistic estimates, or misrepresenting the nature of transactions or financial arrangements with third parties. To achieve an intended result or objective, information relating to contingent liabilities, related party transactions, accounting changes, or any material events, can either be obscured or omitted entirely in the financial disclosures or footnotes.


    Round-Tripping

    This is a fraudulent activities usually conducted between related entities where money is exchanged to create the appearance of a legitimate business transaction, where in reality, it is fake. This fraudulent act is usually perpetrated by the management to artificially inflate revenue, create fictitious transactions, or manipulate the financial information to mislead shareholders, investors, government, and other users of the financial statements. Generally, engaging in round-tripping can result in lawsuits, impair a company’s relationships with relevant stakeholders, and significantly damage its reputation once uncovered.


    Related Party Transactions

    Though, not necessarily a mechanism for fraud, but companies, including multinational entities, can use related party such as subsidiaries, affiliates, or their executives to perpetrate financial fraud. This is particularly possible when assets, goods, or services are exchanged between related parties at inflated prices. Contract prices, loan agreement, leases, and service agreement  between related entities can be manipulated to distort financial results. Because of potential conflict of interest, auditors, or regulatory authorities usually subject related party transaction to thorough investigation.


    Timing Differences

    This involves recording revenue or expenses inappropriately in different periods. Revenue or expenses can be shifted from one period to another in order to achieve a targeted or predetermined earnings. For example, if a company wants to report high profit in a particular period, it can delay closing of books to enable more sales to be generated or allow customers’ invoices to be paid before the books are finally closed for the reporting period or month.


    Manipulating Reserves and Accruals

    Companies can manipulate reserves and accruals, including warranty reserves, provision for doubtful debts to smooth earnings or create the appearance of financial stability.


    Corruption

    This involves conflict of interest, bribery, kickbacks, contract inflation, selling of proprietary information, economic extortion, money laundering, etc., often perpetrated by company’s management or its official in collusion with third parties.

    In Summary

    Financial statement fraud is usually carried out among company directors, employees, and sometimes require collusion with external parties, including auditors, consultants, or vendors. Hence, detection of this kind of fraud will require careful analysis of the financial statements using relevant tools to identify unusual or inconsistent patterns in transactions. Independent verification of key financial metrics may be carried out to spot irregularities.

    Engaging in financial statement fraud have dire consequences for organizations. It can result in financial losses, lawsuits, or erode the company’s reputation. Consider the scandals, and disastrous end of Enron, WorldCom, Wirecard, etc. Understanding ways by which financial statement fraud are been committed, including putting in place, effective detection, and prevention measures, can protect the integrity of financial information and enhance investors’ confidence.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos

  • Strategies for Managing Cash Effectively

    Strategies for Managing Cash Effectively

    Strategies for Managing Cash Effectively

    Cash is the most liquid asset and lifeblood of any business. It represents the receipts and payments arising from business dealings. Therefore, it is essential for companies to have adequate cash balances to execute daily business transactions. Insufficient or dearth of cash can threaten the going concern of a company and impair its ability to settle financial obligations as they become due. Hence, companies must maintain sufficient cash balance to:

    • meet the day-to-day running of the business expenses
    • serve as a cushion against unexpected expenditure
    • guard against working capital problems
    • take advantage of market opportunities.


    If a company does not possess sufficient cash balances, it can limit its ability to operate efficiently and settle short-term debt obligations as they become payable. This may have serious operational repercussions on the business, since working capital is inadequate. Also, the situation can lead to the winding up of the company if it becomes a recurring issue.

    Strategies for Managing Cash

    Managing cash is vital to ensure liquidity and smooth business operations. The effective cash management include:

    • Cash Monitoring & Controlling
    • Investing Surplus Funds (Cash)
    • Establishing A Petty Cash System
    • Offering Trade Discount
    • Automating Invoice Processing

    Cash Monitoring & Controlling

    Cash budget and projection for the receipts and payments should be produced annually and monitored periodically as a way of managing cash effectively. The cash budget and forecast should be prepared separately for the same period under consideration.

    To ensure the budget is not exceeded, the actual cash receipts and payments, including the forecast, should be benchmarked against the budgeted estimate. Where there is difference between budgeted estimate and the actual receipt or payment, the variance should be analyzed, and justification should be provided.

    Monitoring and controlling cash receipts and payments will help businesses to know when there is a cash flow surplus or shortfall, and in effect, improve working capital.


    Investing Surplus Funds

    Managing cash balance is essential for any business. When there is idle fund that is not available for immediate use, the funds should be invested in short-term marketable securities including treasury bills, fixed deposit account, etc. to earn additional return.

    Holding excessive cash balance is an unproductive way of managing assets. Any substantial idle funds should be invested to generate additional returns for the company rather than keeping them in the bank account, yielding zero return. The opportunity cost of not investing idle funds is high and can be damaging to the value of the business.

    In determining the amount of available cash to be invested in short-term marketable securities, high consideration should be given to the working capital requirements of the business.


    Establishing A Petty Cash System

    A small amount of money should be set aside for the day-to-day disbursement of incidental expenses such as supplies, stationery, printing, transport, refreshments, fueling, reimbursement, etc. This will help the business to minimize bank charges arising from frequent bank transactions. The amount to be kept will depend on the size of the business. A large company with different autonomous units will require more cash than a relatively small company. In this case, adequate controls should be put in place to guide against theft and misuse of assets.

    However, maintaining, recording, and reconciling petty cash requires extra work, and can create additional burdens for an employee. Though petty cash is convenient and can be easily accessible for impromptu expenses, but the risk of fraud, misuse, theft, abuse, and evolving technologies (electronic wallets, contactless transactions) have rendered it almost obsolete.


    Offering Trade Discount

    A trade discount can be extended to customers to encourage prompt payment to improve working capital. Early payment discount can attract on time settlement of credit purchases by customers. This will in turn, make cash readily available for use of the business.


    Automating Invoice Processing

    Companies can automate their invoice processing to achieve efficiency and optimum cash conversion cycles. This is because manual processing of invoices may cause delays in sending invoices to customers, loss of invoices, and inefficiencies arising from a high volume of invoices to be processed. Automating invoice processing can help track slow paying customers and request for timely settlement.

    At Greena Partners, our team can collaborate with you to develop strategies to manage your working capital judiciously

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos

  • Key Fundamental Principles for Professional Accountants- A Powerful Reminder

    Key Fundamental Principles for Professional Accountants- A Powerful Reminder

    Greena Partners

    Key Fundamental Principles for Professional Accountants- A Powerful Reminder

    Code of Ethics

    Professional accountants either in public practice or in business are required to comply with the relevant and applicable institutional and governmental laws, rules, and regulations while performing their duties. Professional accountants occupy a fiduciary position in their relationships with employers, clients, and the public. As a result, are expected to act in the best interest of their employers or clients, by ensuring that the right thing is done.

    Generally, the investors and other users of the general-purpose financial statements rely heavily on the financial information produced by the management of a Company through its professional accountant, in making informed economic and investing decisions. Therefore, professional accountants should strive to protect the public interest always. Consistent with the dictate of Financial Reporting Council of Nigeria (FRCN) and the International Federation of Accountants (IFAC) regulations, chartered accountants are required to always act ethically and responsibly, by demonstrating good professional behaviour and ensuring high quality of the general-purpose financial statements.

    Professional accountants are bound by the rules of professional conduct produced by the IFAC or relevant professional accounting bodies including the Institute of Chartered Accountants of Nigeria (ICAN). All chartered accountants, without exception, are expected to comply with the IFAC conceptual framework and apply the fundamental principles in their day-to-day business activities.

    As professional accountants, any action that can damage or bring accounting profession to disrepute should be avoided. Including not engaging in any business, occupation, or activity that impairs or might impair integrity, objectivity, or the good reputation of the profession.

    Fundamental Principles

    The key fundamental principles of accounting profession include:

    • Integrity
    • Objectivity
    • Professional competence and due care
    • Confidentiality
    • Professional behaviour

    Integrity

    Professional accountants have responsibility to demonstrate candor in all their professional and business dealings. As a result, professionals must not only be seen to be truthful but also behave and act honestly. You are a chartered accountant, and hence, must be straightforward in all business relationships.

    Integrity involves showing consistent and strict adherence to strong moral and ethical values. It also involves taking responsibility for one’s own actions, decisions, including the consequences that follow. As a chartered accountant, you are expected to behave responsibly and deal honestly with your colleagues, including clients, customers, suppliers, government and with other third parties.


    Objectivity

    This principle states that professional accountants should not allow bias, conflict of interest or undue influence of others to override professional or business judgments. The financial information produced should be independent, verifiable, and free from biases.

    Objectivity in reporting is essential to make financial statements more useful to all users including investors and its contents more reliable. Lack of independence and objectivity can limit or impair the ability of a professional accountant to be decisive in making recommendations about financial information of a company.

    Some circumstances can create an ethical dilemma for a professional accountant while performing his or her duties. Hence, adequate safeguards should be put in place to ensure that objectivity and independence is not impaired or eroded.


    Professional Competence & Due Care

    When providing professional services, professional accountants are expected to act diligently, and consistent with applicable technical, professional standards, best practices, including evolving technologies. Professional knowledge and skill are needed in exercising sound business and professional judgment while serving clients, customers, and other third parties. To ensure clients or customers receive competent professional service, Company or Firm of chartered accountants should provide appropriate training and supervision to its employees and ensure maintenance of requisite professional knowledge and skill.

    Professional accountants should enroll for  courses, seminars, or workshops periodically to get exposed to the latest trends and best practices, including the Mandatory Continuing Professional Education (MCPE). Confidence is a function of experience. Professional accountants should strive to acquire requisite soft skills that will enhance his or her performance.  A professional accountant should be up to date and conversant with evolving technologies, best practices, and applicable legislation.

    Consistent with the principle of professional competence and due care, professional accountants are required to only undertake significant jobs or tasks for which he / she can obtain or has the requisite competence and experience to do. Chartered accountants should avoid misleading clients, customers, or the public as to the level of expertise and experience in his / her possession. For this purpose, professional accountants are expected to demonstrate diligence and thoroughness in the performance of a task and exercise professional skepticism always.


    Confidentiality

    This principle requires that professional accountants should respect the confidentiality of information acquired during professional and business relationships and that the information should not be disclosed to any third parties without proper and specific authority to do so. The information acquired is only disclosed when there is express or writing permission or having legal or professional duty or right to disclose.

    Confidential information acquired during professional and business relationships should not be used to the benefit of the chartered accountant or any other person. However, professional accountants are only required and entitled to use prior knowledge and experience gained when he / she changes jobs or acquires new clients or customers.


    Professional Behaviour

    Professional accountants are required to comply with relevant laws, rules, customs, and regulations and should eschew any action or behaviour that impairs, appears to impair, or might erode the reputation of the accounting profession. Chartered accountants should avoid making unsubstantiated claims, disparaging comments, or discrediting the work of other professional colleagues. It is unprofessional to make exaggerated assertion about one’s service offerings, qualifications, or experience gained.

    A chartered accountant has a responsibility to shun any action that a reasonable and an informed third party, having knowledge of all relevant information, would conclude negatively about the good reputation of the profession.

    Conclusion

    Occasionally, professional accountants may find themselves in a compromising situation that create an ethical dilemma while performing their duties. In this circumstance, the strict adherence to the underlying fundamental principles of accounting profession and the application of the relevant safeguards, will have far-reaching effect in protecting your reputation and that of the profession you represent.

    Hence, it is essential for Companies or Firms to develop a code of ethics and business conduct and demand total compliance Firmwide, including taken exception to any members, partners, directors, or employees who deal unscrupulously or violate the law to achieve results. Firm should strongly prohibit any distortion and manipulation of books and records and demand total, correct, fair, and timely disclosure of financial information in reporting.

    At all times, professional accountants must be above board and demonstrate a high level of professionalism in the conduct of their duties or business relationships. Professional accountants are ambassadors of accounting profession. Hence, we must protect and guard the longstanding reputation of the profession jealously and avoid any action that may damage or erode it.

    When Do You Need the Service of a Chartered Accountant?

    A chartered accountant is needed in business for a rewarding and profitable outcome. Professional accountant will provide the requisite business and financial strategies to the organization and guide the company against any potential risk exposure. The global business environment is becoming challenging and volatile. Hence, chartered accountants are needed more than ever to help businesses mitigate risks and act as enablers to achieve corporate strategic goals.

    To avoid risk of financial losses, you need the service of a professional accountant to help you design tailor-made organizational processes and procedures to preclude financial leakages and develop a policy document known as standards of business conduct to serve as business operating manual.

    Kindly reach out to us at Greena Partners, should you need chartered accountant services

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos

  • How To Effectively Manage Working Capital

    How To Effectively Manage Working Capital

    Working Capital Management

    How To Effectively Manage Working Capital

    Every business entity, be it large or small, private, or public, needs sufficient working capital to be able to run smoothly. Lack of or inadequate working capital can impair the ability of a company to operate on a going concern basis. Generally, company needs working capital to pay salaries, purchase inventories and supplies, settle short-term debt obligations as they become due, etc. When a business is unable to accomplish any of these, some operating activities of the company may be curtailed. Imagine a company in the production process, and suddenly realized that the material is exhausted or finished. Certainly, this occurrence will disrupt production, and may result in loss of revenue or may even erode the reputation of the organization. Hence, it is essential that adequate working capital is available to ensure smooth production run and achieve operating efficiency.


    Working Capital Versus Working Capital Management

    Working capital may be described as a difference between current assets and current liabilities. It is the amount required for the day to day running of a business. On the flip side, working capital management represents a judicious and efficient management of each component of current assets and current liabilities including inventory, account receivable, cash & cash equivalent, account payable, short-term debt etc. to ensure the liquidity of the company. The primary purpose or objective of working capital management is to guarantee sufficient cash flow is available to meet short-term operating costs and debt obligations. Efficient working capital management is intended to ensure smooth financial operations, improve earnings, and increase profitability of a company.


    Working Capital Cycle

    This is also known as operating cycle or cash operating cycle. It is described as the length of time between when cash is paid to acquire raw materials and when cash is finally received from debtors through sales. The longer the operating cycle, the longer capital is tying down without earning return on it. Therefore, companies should strive to reduce their working capital cycle by collecting receivables promptly or delaying accounts payable, if possible.

    Below is the pictorial representation of working capital cycle:

    Working Capital Cycle

    To sustain the liquidity, profitability, and going concern status of a company, each component of current assets and current liabilities in the statement of financial position must be managed effectively and given due consideration.


    Cash Management

    Cash is the most liquid asset of an organization. It represents the lifeblood of any business. The lack of which can collapse a company. Therefore, companies must maintain sufficient cash balance to:

    • meet the day-to-day running of the business activities
    • serve as a cushion against unexpected expenditure
    • guard against working capital problems
    • take advantage of market opportunities.


    If a company does not possess adequate cash balance, it can impair its ability to operate efficiently and settle short-term debt obligations as they fall due. This may have serious operational repercussions on the business because working capital is inadequate. This situation can also lead to the winding up of the company if it becomes a recurring issue.

    However, when a company has idle funds that will not be needed or used in the next 3months or more, the funds should be immediately invested in short-term marketable securities including treasury bill, fixed deposit account, etc. to earn return. Holding too much of cash or bank balance is an unproductive way of managing asset. Any substantial surplus funds should be invested to generate additional profit for the company rather than keeping them in the bank account, yielding zero return.


    Cash Monitoring & Controlling

    Cash projection and budget for receipts and payments should be produced annually or periodically as a way of managing working capital effectively. The cash budget and forecast should be prepared separately for the same period under consideration. To ensure the budget is not exceeded, the actual cash receipts and payments including the forecast, should be benchmarked against the budget estimate. Any associated variance should then be analyzed and justified. Monitoring and controlling of cash receipts and payments will help businesses to know when there is cash flow surplus or shortfall, and in effect, improve working capital.

    Inventory Management 

    This involves the method of ensuring that the right quality and quantity of the relevant inventories is available at the right time and at the right place. Inventory includes raw materials, work-in-progress and finished goods that are ready for sale. It is one of the most critical assets of a business because it represents the primary source of revenue generation. Hence, efficient inventory control will enhance working capital.


    Reasons For Holding Inventory

    Companies have divergent reasons for keeping inventories and some of which include:

    • To ensure smooth production run
    • To meet regular demand
    • To take advantage of bulk purchase discount
    • To even out seasonal variation in demand
    • To take benefit of unexpected scarcity in the product


    Inventory Costs

    These are costs associated with inventory management. The component of Inventory costs include:


    Ordering Cost

    These are costs incurred when an order is placed up to the point of receiving the goods into the warehouse. Examples of ordering costs include the following:

    • Cost of issuing purchase order e.g., remuneration of purchasing dept. staff
    • Transportation cost
    • Cost of getting payment to the supplier
    • Communication cost g., telephone bills, data etc.
    • Cost of loading or offloading the items


    Carrying Cost

    This is also known as stock-holding cost. They are costs incurred whenever material is stored in the warehouse. Carrying cost per unit is directly related to purchase price per unit. Examples of carrying cost include:

    • Initial investment- capital outlay
    • Cost of renting the warehouse / store
    • Insurance and audit costs
    • Warehouse maintenance
    • Damages and pilferages
    • Documentation cost e.g., stocktaking
    • Deterioration and obsolescence


    Stock-out Cost 

    These are costs incurred when customers’ demand cannot be met because the stock is exhausted. They are the opportunity cost of not having a stock when customers are ready and willing to buy. Examples of stock-out cost include:

    • Loss of revenue
    • Loss of reputation or goodwill
    • Loss of experienced staff
    • Loss of trade secret to competitors due to loss of staff


    Purchase Cost

    This is the actual cost of the items placed in stock. The cost per unit of the items may be fixed if no quantity discount is allowed. But the cost will vary if quantity discount permitted.


    Objectives of Managing Inventory

    Inventory management is extremely important for any organization. The primary purpose of which is to ensure that stock levels are maintained so that the total relevant costs of inventory mentioned above, are kept at the barest minimum. However, the objectives that companies may want to achieve in managing inventory to ensure efficient working capital may include:

    • To minimize capital investment in inventory by purchasing only requisite items
    • To minimize risk of loss due to obsolescence, deterioration, etc.
    • To supply the required materials continuously
    • To minimize the cost associated with inventory
    • To minimize the risk of under and over stocking of material
    • To maintain systematic record of inventory

    Accounts Receivable Management

    The objective of managing account receivables is to ascertain the optimum level of trade credit to be offered to customers and timely collectability of such credit. Offering credit to customers is intended to increase sales and in effect profitability. Customers’ loyalty are assured if customers are given opportunity to purchase on credit.

    However, companies should design credit policies that will be consistent with the overall objective of the organization, industry standards, and best practices. The guidelines should expressly specify the credit terms for the collectibles. For instance, a company may adopt 15, 30, 45days, or more as credit terms. A responsible person or department within the organization should be assigned the responsibility of ensuring timely collection of the collectibles.

    Offering too much credit or having too liberal credit terms may result in high bad debts, and which may result in liquidity problems and loss of income to the company. On the other hand, if the credit terms are too strict and unfriendly, customers may patronize the competitors where credit conditions are more favorable. This may result in loss of customers and revenue. Therefore, companies should strike a balance and design suitable credit terms that the current and potential customers will be willing to accept. Trade discount can also be extended to customers to encourage prompt payment to improve working capital.

    Also, companies can automate its invoice processing to achieve efficiencies and optimum cash conversion cycles. This is because manual processing of invoices may cause delay in sending invoices to customers, loss of invoices, and inefficiencies arising from high volume of invoices to be processed.

    Accounts Payable Management

    Accounts payable represents the amount a company is owing to its suppliers or vendors arising from trade credit. It is an arrangement by which a business purchase goods on account for credit, and settlement to the supplier is deferred into an agreed future date. Usually, suppliers can give credit for 15, 30, 45, 60 days or more, depending on the supplier’s credit policy. A discount is allowed if payment is made within a specified number of days, otherwise, the full amount will be due at a specified date. For instance, the terms of “3/10, net 30” means that a 3percent discount is granted if the invoice amount is paid within 10days; otherwise, the full amount will be paid on the 30th day. The terms of discount and credit policy differ among companies, depending on the industry, level of competition and market conditions.

    The earlier the settlement of trade credit to vendors, the better the creditworthiness, and the higher the future opportunities that will be extended. This will also enhance the flow of working capital because there will be regular supply of materials, high-quality products will be provided, and there will be on-time delivery.

    However, if credit is delay beyond the agreed term, it will improve working capital ratios, but may damage the reputation of the company, worsen business relationships with suppliers, require firm to pay cash before supply, and impair its ability to enjoy credit facilities on a going concern basis.

    Companies should avoid the tendency of delaying payments to vendors for goods supplied, except it is impracticable. And when there is going to be delay in invoice payment, suppliers should be informed immediately and agreed on the revised payment date.

    Short-Term Financing

    Trade credit is the cheapest and most important source of short-term finance for many companies, especially where the required funds is not readily available. Identifying the appropriate source of financing inventory may be very challenging. In this case, trade credit will become handy to finance working capital. However, if there is no credit facility from supplier, it may be necessary to utilize bank loan or overdraft facility.

    A firm’s suppliers may want to offer discounts to encourage early settlement. This opportunity should be grabbed if the discounts will benefit the company the more. However, if the company is short of cash, it might decide to maximize the credit period granted by the suppliers, irrespective of the settlement discounts offered.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business
    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos

    SIGN UP below to receive Business Articles from Adda

  • Who is a Chartered Accountant?

    Who is a Chartered Accountant?

    Greena Partners

    Who is a Chartered Accountant?

    Accounting profession is a very challenging, respected, and interesting discipline that is designed to bring out the best in an average aspiring-chartered accountant. The journey to become a chartered accountant may be tough, due to the rigorous level of examinations to be undertaken, but the end result is highly rewarding. The professional accountant jobs are in high demand across public and private organizations anywhere in the world. Chartered accountants occupy positions such as auditor, financial accountant, management accountant, cost accountant, finance analyst, finance specialist, project accountant, business consultant, financial advisor, finance manager, financial controller, finance director, chief financial officer, or chief executive officer etc., depending on your years of experience and the size of the organization.

    The professional accountants are decision makers, trusted advisors, and business leaders positioned to create increasing value for their companies. A chartered accountant occupies a fiduciary position within an organization, and as a result, are expected to act in the best interest of their employers or clients. Professional accountants are responsible for preparing and reporting the financial statements of their entities in which the investors and other users rely upon. For this reason, they are required to protect the public interest. Generally, high expectation is placed on a chartered accountant to act ethically and responsibly by demonstrating good professional behavior and ensuring high quality of the general purpose financial statements.

    Who Is a Chartered Accountant?

    A chartered accountant is a professional accountant that has been trained by a recognized accounting body in a country, after passing the prescribed examinations and have been so inducted and provided with a certificate by the institution. In Nigeria, the Institute of Chartered Accountants of Nigeria (ICAN) and the Association of National Accountants of Nigeria (ANAN) are the two bodies recognized by the act of parliament. By convention, and according to the dictate of accounting profession, only chartered accountants or members of the institute are permitted to use the designation of Associate Chartered Accountant (ACA) or Fellow Chartered Accountant (FCA) for ICAN, and Certified National Accountant (CNA) or Fellow Certified National Accountant (FCNA) for ANAN.


    Some Other Professional Accounting Bodies

    Other countries in the world have their own recognized professional accounting bodies including:

    • Institute of Chartered Accountants of Ghana (ICAG)
    • South African Institute of Chartered Accountants (SAICA)
    • Institute of Chartered Accountants of India (ICAI)
    • Chinese Institute of Certified Public Accountants (CICPA)
    • Institute of Chartered Accountants in England and Wales (ICAEW)
    • Association of Chartered Certified Accountants (ACCA)
    • American Institute of Certified Public Accountants (AICPA)
    • Canadian Institute of Chartered Accountants (CICA) etc.


    Chartered accountants are generally bound by the rules of professional conduct produced by the International Federation of Accountants (IFAC) or relevant professional accounting bodies. A professional accountant is required to comply with the conceptual framework, and apply in their day-to-day activities, the fundamental principles of:

    • Integrity
    • Objectivity and independence
    • Professional competence and due care
    • Confidentiality
    • Professional behavior

    Is Accounting Graduate a Chartered Accountant?

    An accounting graduate, or a person that is performing accounting roles in an organization is an accountant and NOT a chartered or certified accountant, irrespective of his / her many years of experience on the job. As such, no specific professional qualification is required to enjoy the title of accountant. However, Accountants are not allowed to use ACA or CA designate because they do not possess the requisite training and professional qualification.

    Professional Accountants in Public Practice

    These are chartered accountants working as members, partners, or employees of a practising accounting firm to render professional services including accounting, consulting, assurance, tax, investigation, forensic accounting, etc. to public and private organizations. Professional accountants in public practice are expected to comply with all fundamental principles of the profession and avoid any action that can damage or bring accounting profession to disrepute. 

    In accordance with the code of ethics for professional accountants of International Federation of Accountants (IFAC), a professional accountant in public practice should not engage in any business, occupation, or activity that impairs or might impair integrity, objectivity, or the good reputation of the profession and as a result would be incompatible with the rendering of professional services. A chartered accountant in public practice should be aware of some certain situations or events that can potentially threatened the fundamental principles of the profession including:

    • Self-interest threat
    • Self-review threat
    • Advocacy threat
    • Familiarity threat
    • Intimidation


    Professional Accountants in Business

    These are chartered accountants employed or engaged by private or public entities to provide strategic financial and business solutions to aid management decision making. Professional accountants in business use their professional skills and the knowledge of the business, industry, and economic environment in providing support to management to develop corporate strategy, optimize costs, improve revenue, design measures to mitigate risks, and provide professional advice to enhance the overall value of the business. Particularly as a board member of a big or quoted company, a chartered accountant is seen as being representing the interest of the shareholders in the company. Hence, a chartered accountant is expected to act in the best interest of the public and strive to increase the value of the company to enhance owners’ equity value.

    When Do You Need the Service of a Chartered Accountant?

    A chartered accountant is needed in business for a rewarding and profitable outcome. Professional accountant will provide the requisite business and financial strategies to the organization and guide the company against any potential risk exposure. The global business environment is becoming challenging and volatile. Hence, chartered accountants are needed more than ever to help businesses mitigate risks and act as enablers to achieve corporate strategic goals.

    To avoid risk of financial losses, you need the service of a professional accountant to help you design tailor-made organizational processes and procedures to preclude financial leakages and develop a policy document known as standards of business conduct to serve as business operating manual.

    At Greena, we pride ourselves with highly experienced and committed professionals willing and ready to collaborate with businesses to create value

    SIGN UP below to receive compelling articles to improve your business

    info@greenapartners.com

    +234 (0) 901 610 3132
     

    Postal Code: 100213

    74 Ogunnusi Road, Ojodu Ikeja, Lagos